Overcapacity is forcing a clean-tech shakeout
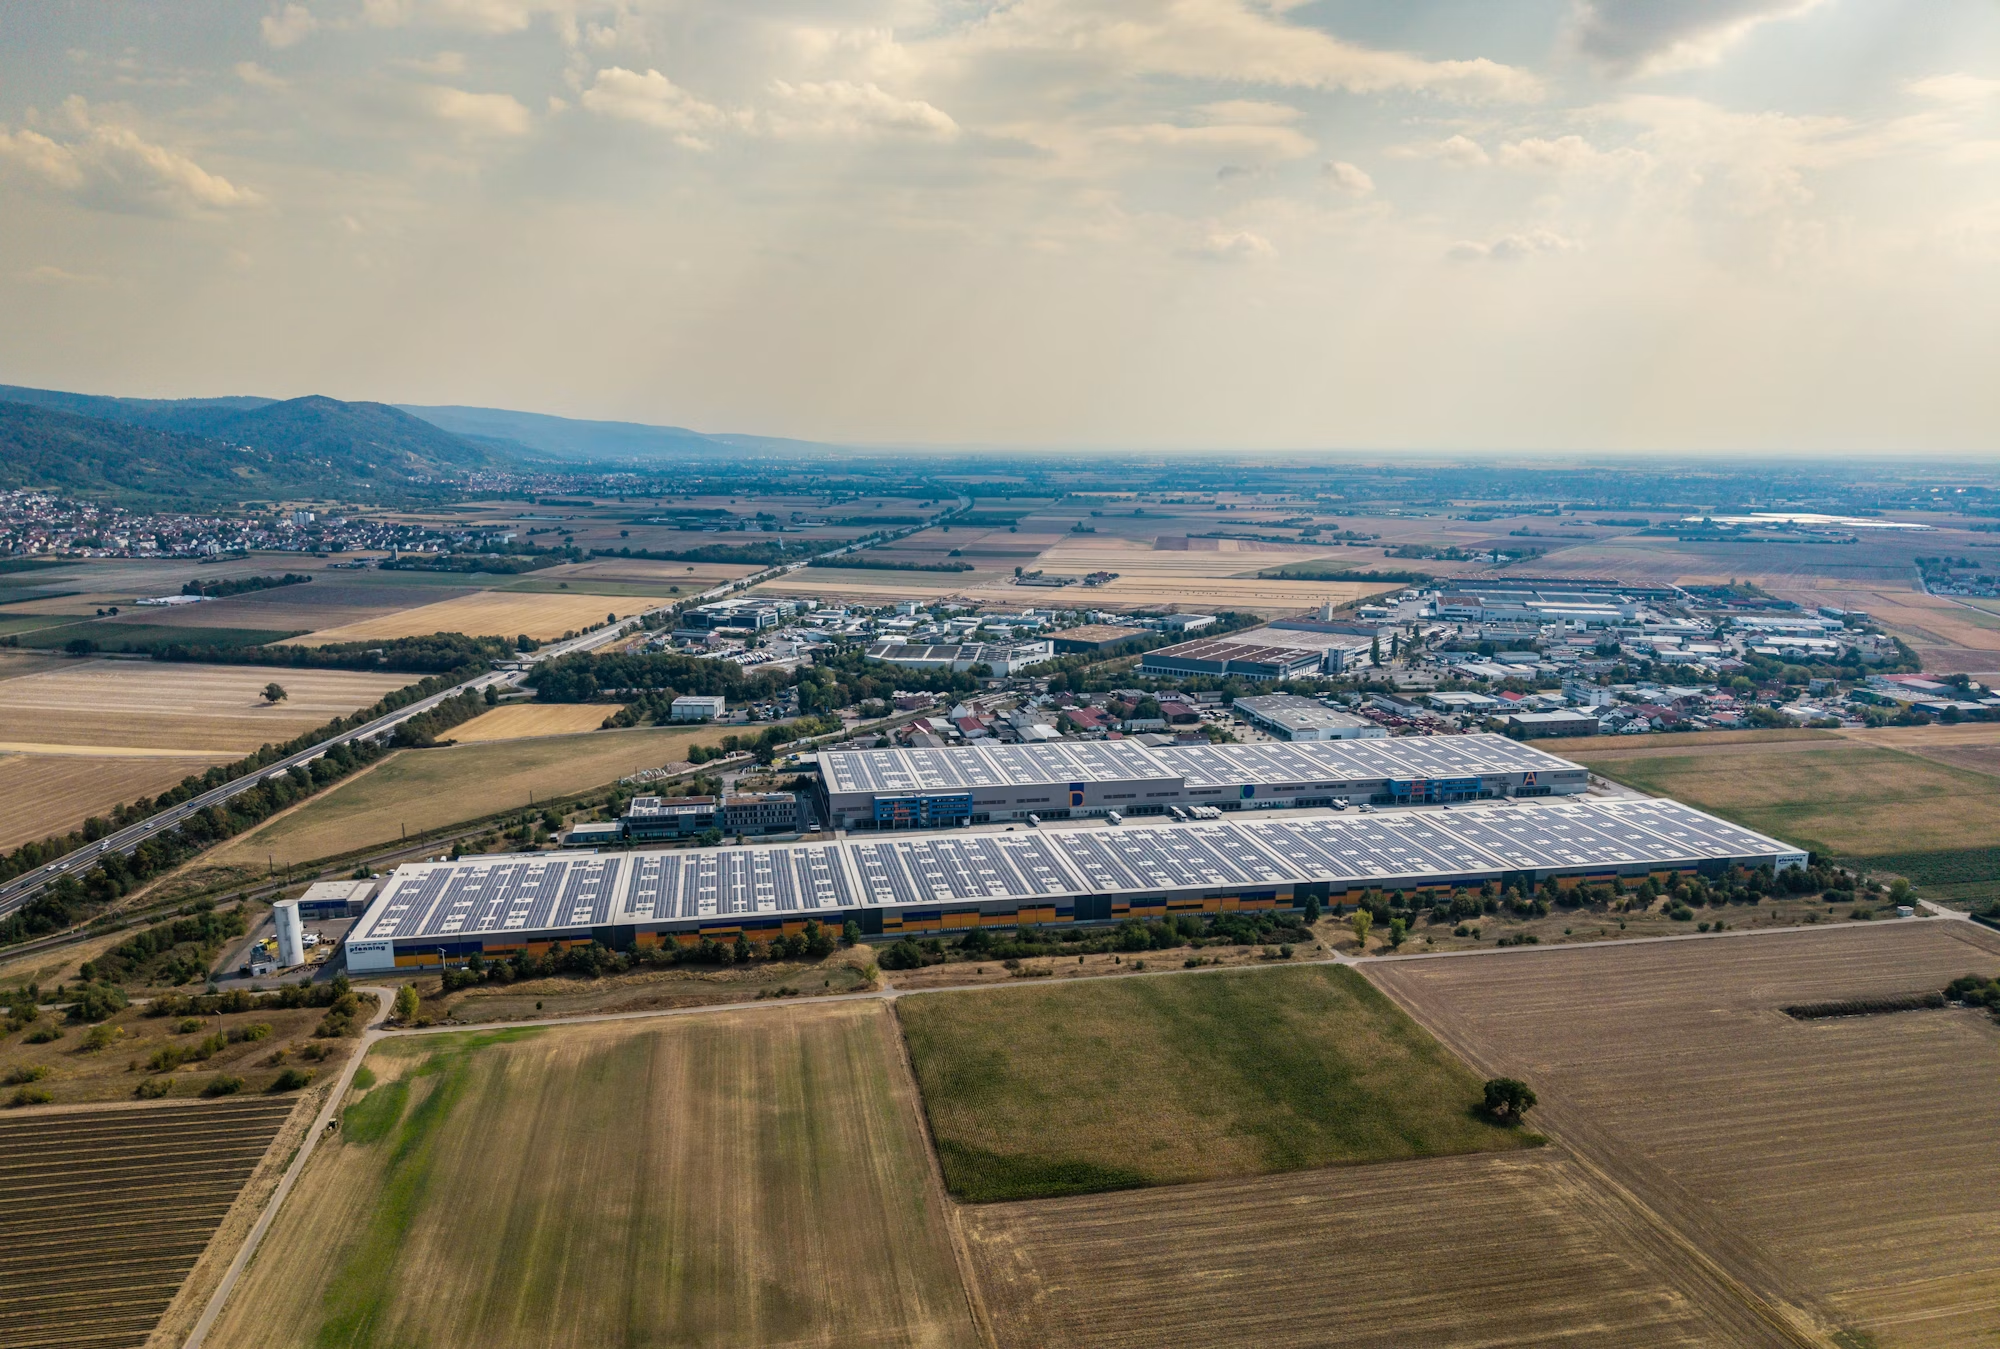
China has built roughly 1,200 GW of annual solar manufacturing capacity, close to twice current global demand. Polysilicon plants operated at only 44% utilisation in 2025, while an estimated 570,000 to 600,000 tonnes of inventory remained unsold in early 2026. That stock could supply as much as 300 GW of unbuilt modules.
Module prices have fallen to around 40% below production cost, contributing to heavy losses at major producers including LONGi, Tongwei and Aiko Solar.
A managed consolidation plan has stalled
In January 2026, China's antitrust regulator blocked a CNY 50 billion plan under which six leading polysilicon manufacturers would have jointly funded the closure of 500,000 to 600,000 tonnes of excess capacity.
Regulators later froze approvals for new battery plants after 2,608.5 GWh of new capacity was approved during the first seven months of 2026. That figure already exceeded China's entire battery output of 1,755.6 GWh in 2025.
What the restructuring means for workers
Without an agreed consolidation mechanism, the adjustment is likely to involve idled plants, pressure on wages and sharper competition for roles linked to sodium-ion, perovskite and solid-state technologies. These emerging formats remain exempt from new consumption taxes applied to conventional cells.
Mandatory efficiency standards due to take effect on 1 January 2027 could accelerate the shakeout. For workers across China's clean-tech manufacturing base, the transition is becoming a test of how quickly skills can move from oversupplied production lines into newer technologies.
Sources:
CMGM — China's Solar Overcapacity: The $7B Fix That Got Blocked — 14 August 2026
Gokhshtein — China Halts Battery Plant Approvals as 2,600 GWh Oversupply Approaches — 10 September 2026
Bruegel — Understanding the global clean tech manufacturing slowdown — 11 May 2026